Hi, I'm Ngoc Minh NGUYEN
I'm a quantitative risk analyst based in Bordeaux, France. Outside of work, I build independent finance tools — backtesting engines and portfolio risk dashboards. This page tracks my education, experience, and the things I've built.
Currently learning: derivatives and option pricing.
Education
Master 2 Advanced Studies and Research in Finance - Research Track (M.Sc. in Finance)
2023–2024Ranked first in class, graduated with the mention Très Bien (highest honors).
Coursework in quantitative finance, risk management, and financial econometrics. Thesis on Machine Learning in French stock markets under the supervision of Mr. Souleymane LAMINOU ABDOU.
Msc of Engineering in Applied Mathematics
2019–2024Coursework in applied mathematics, numerical methods, and optimization. Thesis on the application of Applied Mathematics in Model Risk Management at BNP Paribas.
Exchange Program in Mathematics Department
Feb 2023 – Jun 2023Coursework in Business Intelligence, Data Science, and Bayesian Statistics. GPA: 90.33/100.
Baccalauréat, Mathematics Option
2016–2019Experience
Quantitative Risk Analyst
Nov 2024 – PresentLead the monthly IFRS 9 provisions reporting, ensuring reliability and on-time delivery.
Analyze the Retail portfolio (exposure above €100M), identifying the main risk concentrations.
Run impact simulations on EAD, LGD, and PD.
Optimize existing reporting tools, cutting the reporting process from several days to 2 hours.
Study the risk factors driving PD changes across customer segments.
Tech stack: SAS, Python, VBA, Power BI.
Model Risk Analyst
May 2024 – Oct 2024Developed a Model Risk Rating (MRR) model used to rank the risk of more than 100 models: data collection, machine learning, hyper-parameter tuning, and continuous optimization.
Data Scientist
Jun 2023 – Sep 2023Skills
- Programming
- Python (pandas, scikit-learn, Streamlit), SAS, VBA, JavaScript
- Quantitative methods
- Credit risk (PD, LGD, EAD), IFRS 9 provisioning, model risk, VaR / expected shortfall, Monte Carlo simulation, stochastic calculus, machine learning, credit scorecards (WOE / IV)
- Tools
- Power BI, Dataiku, Bloomberg, Git / GitHub Actions
- Languages
- Vietnamese (native), English (full professional), French (full professional)
Projects
Projects, marked live as they ship.
| Sym | Name | Type | Status |
|---|---|---|---|
| PULSE |
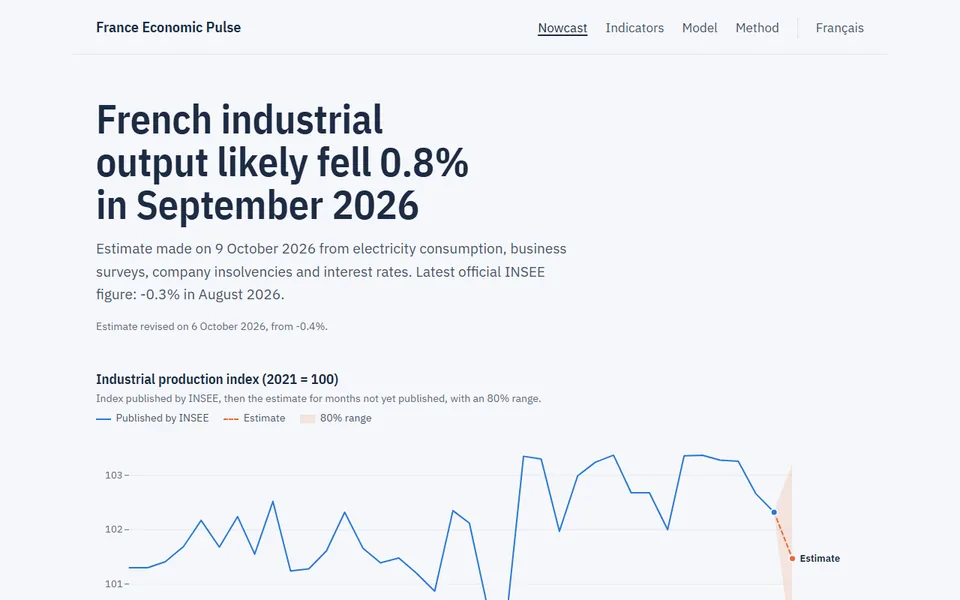
France Economic Pulse
Daily open-data nowcast of French industrial production — 5% lower error than a naive benchmark over a 127-month walk-forward backtest.
|
Macro / Nowcasting | ● LIVE → SOURCE WRITE-UP |
| PD |
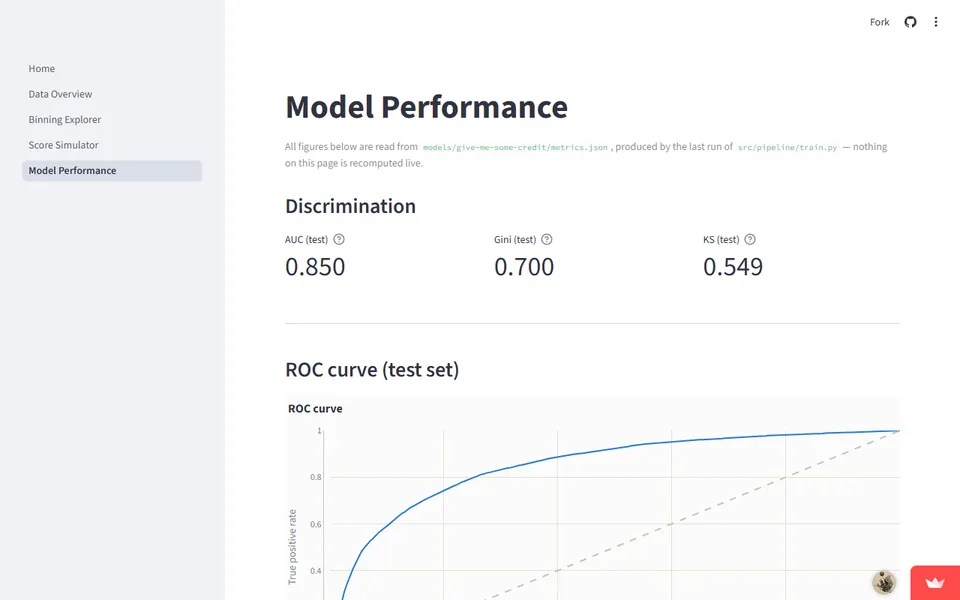
PD Credit Scorecard
Interactive PD scorecard on 150k Kaggle loans — WOE binning, a score simulator, and validation (test AUC 0.85, Gini 0.70, KS 0.55).
|
Credit Risk / Scoring | ● LIVE → SOURCE May take ~30 s to wake up |
| SDE |
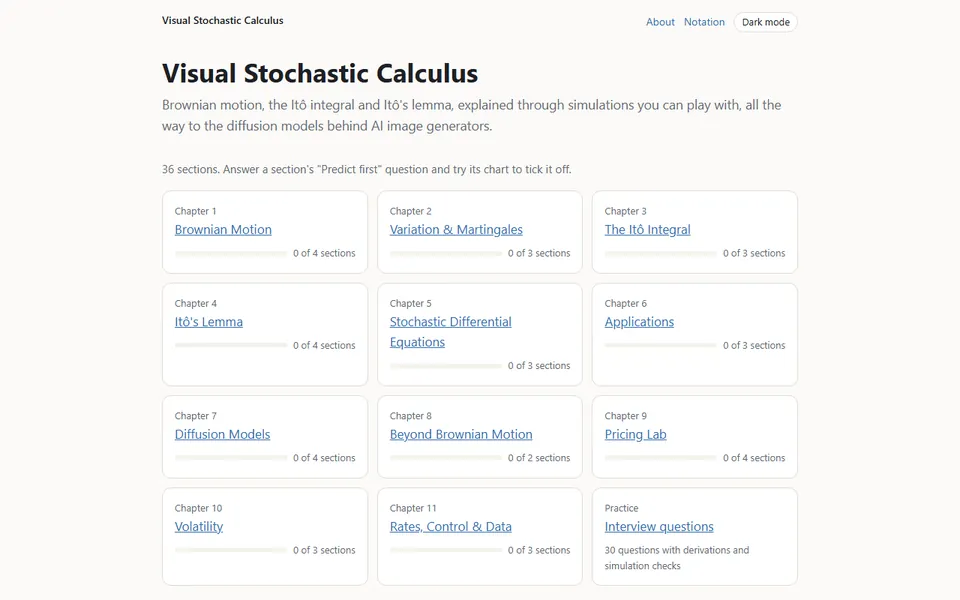
Visual Stochastic Calculus
From Brownian motion to Black–Scholes, Heston, and diffusion models — 11 interactive chapters with runnable Python.
|
Stochastic Calculus / Learning | ● LIVE → SOURCE |
| DIST |
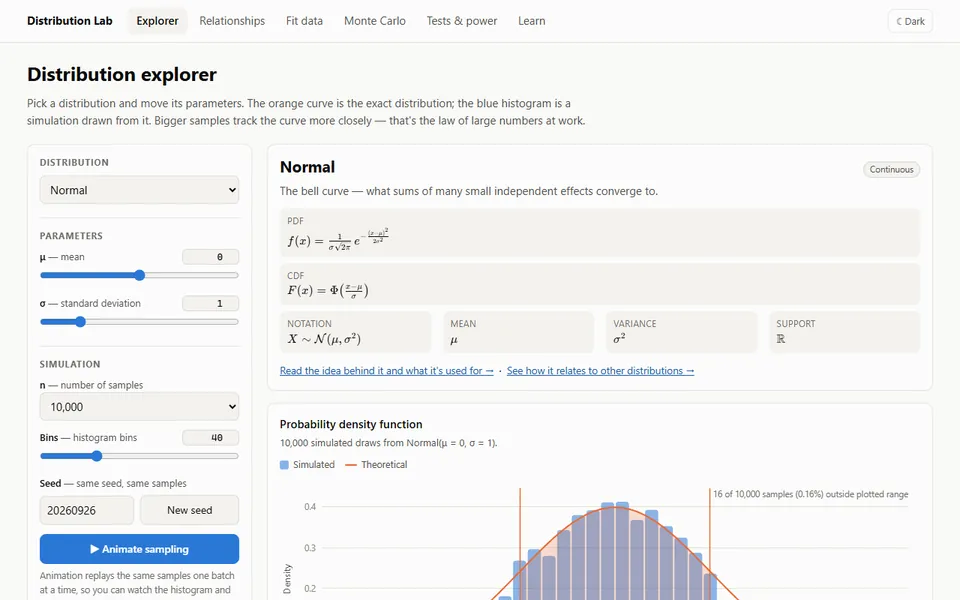
Distribution Lab
16 probability distributions to explore, fit to data by MLE, and run through Monte Carlo VaR scenarios.
|
Probability / Statistics | ● LIVE → SOURCE |
| Earlier projects | |||
| SENT |
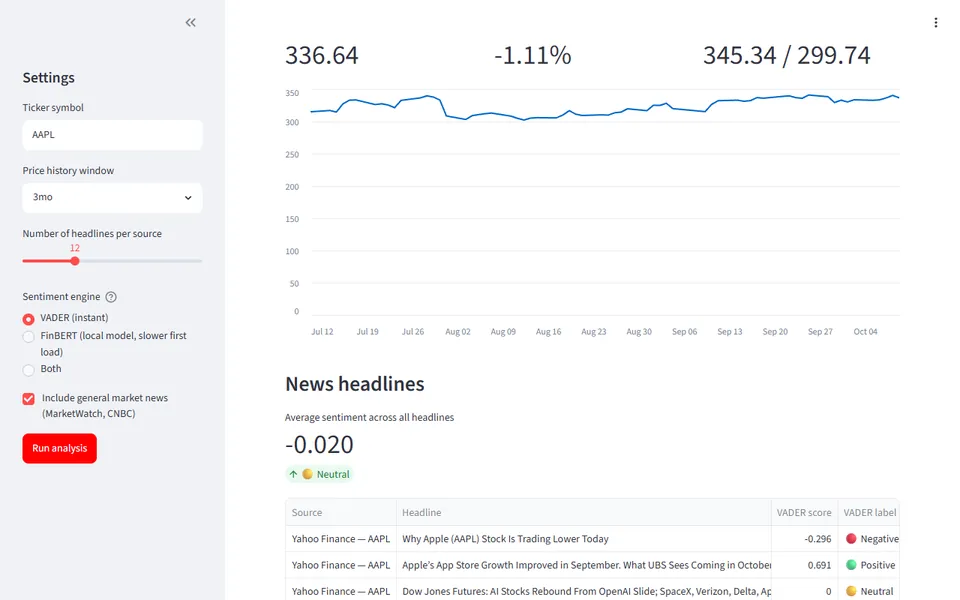
Financial Sentiment Dashboard
Market data + financial news, scored locally with VADER & FinBERT — no API cost.
|
NLP / Markets | ● LIVE → SOURCE May take ~30 s to wake up |
| RISK |
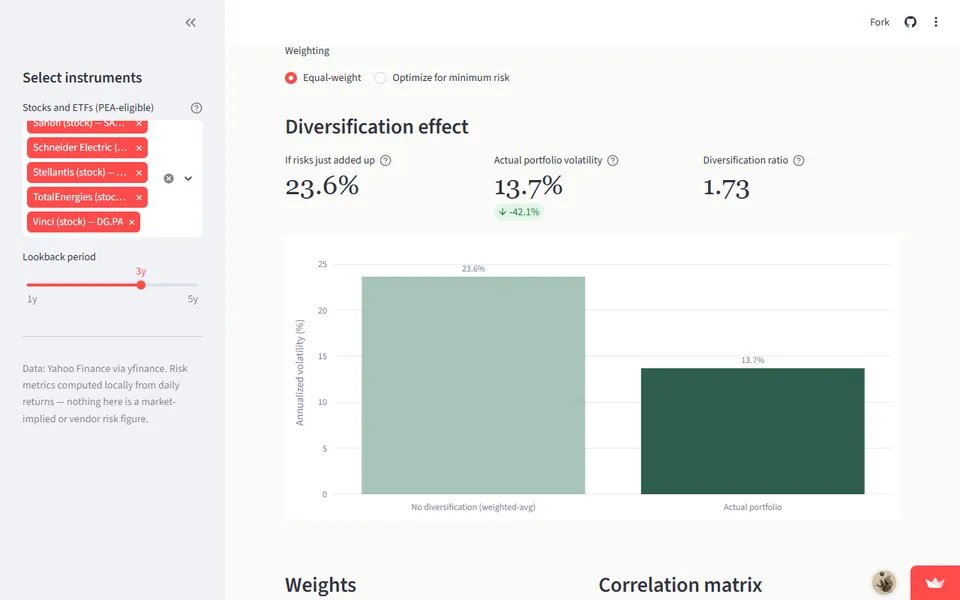
PEA Risk Lab
Risk analysis for 20 French stocks and 7 UCITS ETFs — VaR, CVaR, beta, and a minimum-variance optimizer.
|
Risk / Portfolio Management | ● LIVE → SOURCE May take ~30 s to wake up |
| SIM |
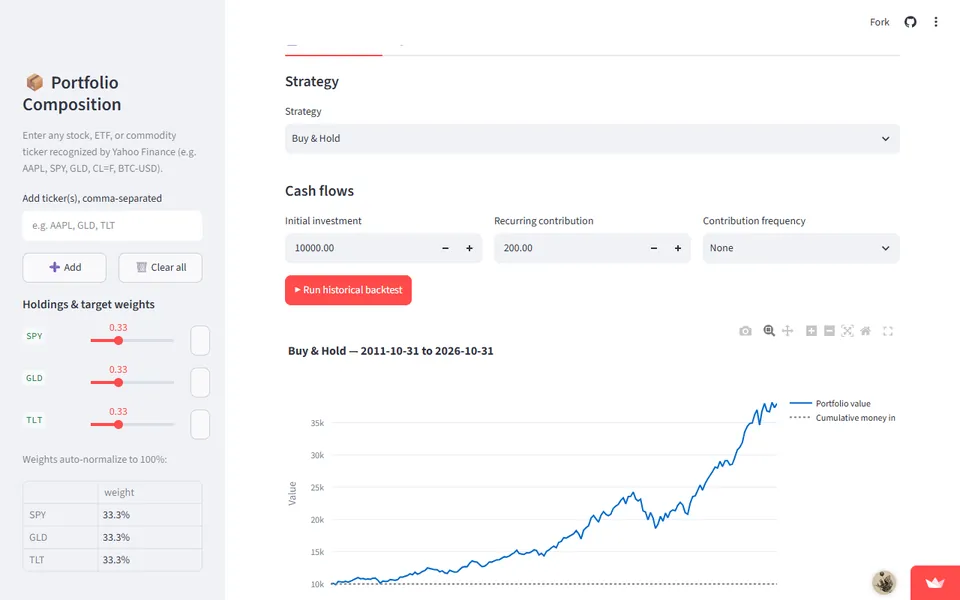
Strategy Simulation
Market data + strategy testing — DCA, momentum, and a 1,000-path block-bootstrap Monte Carlo.
|
Strategy / Backtesting | ● LIVE → SOURCE WRITE-UP May take ~30 s to wake up |
···· Next position opening soon — every project above links to a live app or its source code.
Certifications
Core Designer Certificate Verify ↗
Jul 2024Bloomberg Market Concepts Verify ↗
Nov 2023AMF Certification
Competitions
Cod'INSA
2024Hanoi Open Mathematics Competition (HOMC)
2015Contact
Open to conversations about quantitative finance, risk tooling, or collaboration.
minhnn238@gmail.com · github.com/nnm-psd · linkedin.com/in/minhnn238